Military PCS Home Buying & Selling
Military PCS Realtor in Colorado Springs
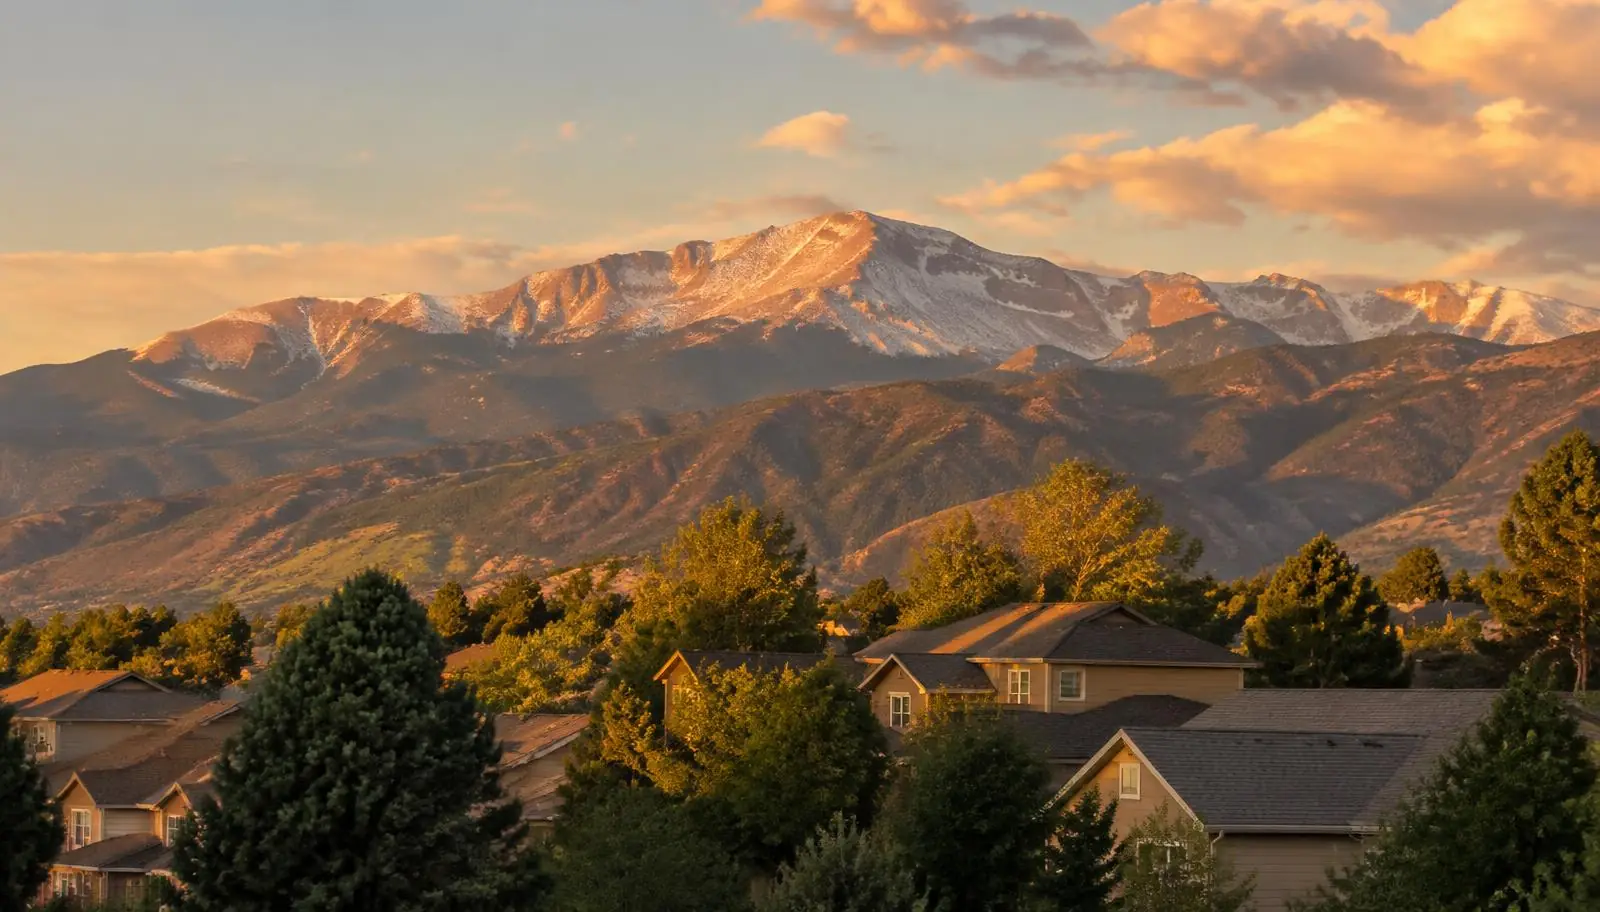
PCSing to or from Colorado Springs? Whether your orders are to Fort Carson, Peterson Space Force Base, Schriever Space Force Base, Cheyenne Mountain Space Force Station, or the U.S. Air Force Academy, I help you buy, sell, or rent around your timeline, including from another state or overseas.
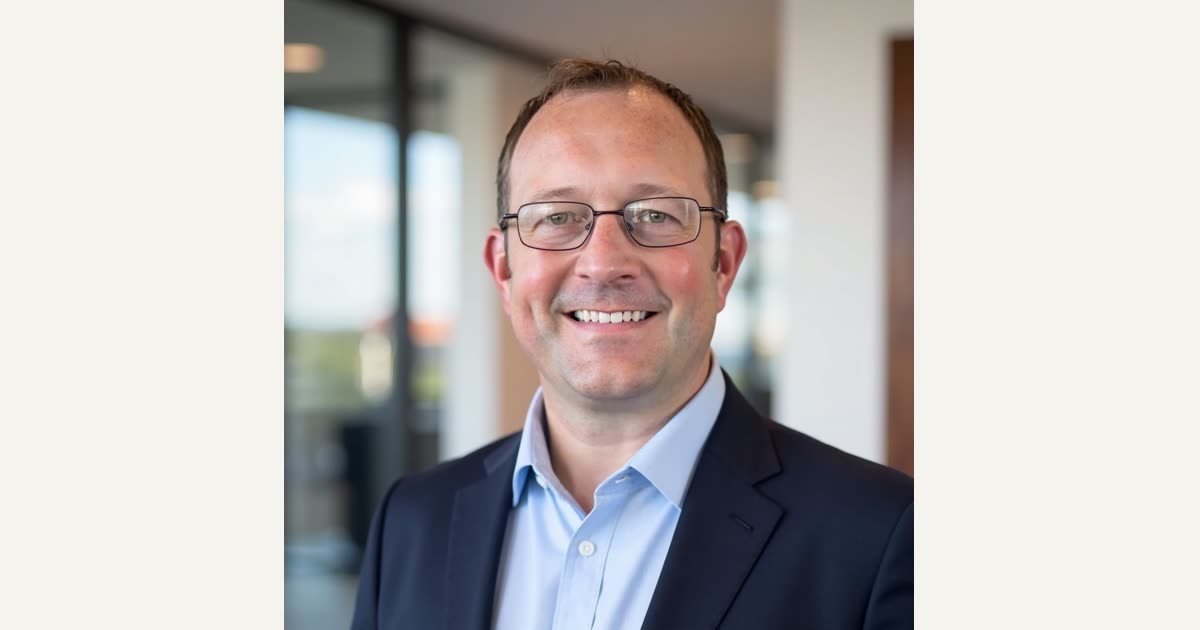
Answers by Weldon Hobbs · Team Hobbs Realty
MRP (Military Relocation Professional) · USAFA graduate and retired Air Force veteran · 10+ military moves with his family
More about Weldon →My family and I made more than 10 military moves, so I plan every move around what your orders, your budget, and your next assignment actually look like.
“They understand the stressors of a PCS and when we had to leave with a few loose ends on our house in Colorado Springs, they were with us every step of the way and helped out in many ways even after we left for our next duty station.”
“Based on our situation and the numbers, he recommended not purchasing right now. No pressure, no sales pitch—just honest guidance that helped us avoid a purchase that wasn’t right for this season of life.”
Who it's for: Guardians, Soldiers, Airmen, and their families PCSing to or from Colorado Springs, plus veterans and military retirees
Coming here: a planning call, video walkthroughs from wherever you're stationed, then a house-hunting visit or a remote purchase
Leaving: we run the numbers on selling or renting, and I handle the sale after you've gone, including a remote closing
VA buyers: I work alongside VA-experienced lenders and know what to watch for on VA purchases; I'm not a loan officer
The honest math of buying on PCS orders
Colorado Springs is an expensive place to buy. As a rule of thumb, I recommend buying only if you can hold the home for about five years. That creates a conundrum, because most assignments are shorter, often about three years. If you sell after a short hold, the costs of buying and selling can mean bringing money to closing.
That's why I recommend buying with a renter's mindset from day one. If you might rent the home out when you leave, the numbers need to come close to working: the full monthly cost against what the home could likely rent for. That shapes which home you buy and how you finance it.
Optimize the loan up front. Many military buyers use a VA loan. The VA funding fee drops when you put 5% or more down, and if rates fall later, VA's streamlined refinance (the Interest Rate Reduction Refinance Loan) can lower your rate, with its costs able to be rolled into the loan. Your loan officer is the one to run these options, and our first conversation is where we make sure you know to ask.
Pick a home that would rent well. Look at what makes a home easy to rent: its location and commute to the bases and major employers, its layout and condition, any HOA rules on renting, and the full monthly cost.
Keep a reserve. If you rent it out, I recommend setting aside $10,000 to $15,000 for the day something breaks. It's not if, it's when.
If you're willing to treat the home as a long-term investment and ride it out, buying here can work well. If you're not, renting may be the better call, and that's a fine answer. See rent or buy in Colorado Springs and how BAH affects what you can afford.
How I help you PCS to Colorado Springs
1. A conversation first
Before we talk about homes, I start by understanding your life goals and your requirements: your report date, your family's needs, how long you expect to be here, and whether you'd keep the home as a rental. Then we bring in the lender. I'll give you three VA-experienced lender options to talk with, and you're free to choose anyone.
2. Search and video walkthroughs from wherever you're stationed
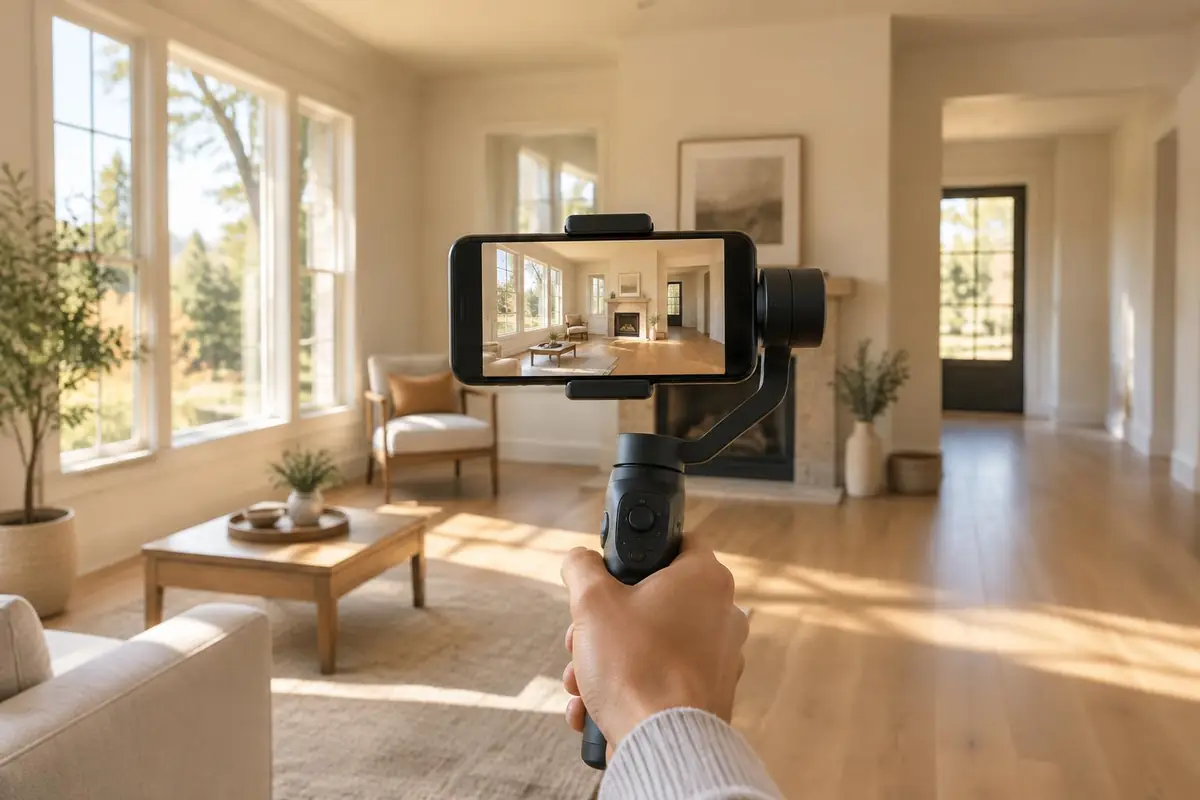
I set up your search and we talk about listings as they come up. When a home looks promising, I do a quick video walkthrough so you can decide whether it's worth seeing in person. I film with a stabilized camera in landscape, live on FaceTime or recorded and shared privately on YouTube, and I point out the things photos skip: the air conditioning, garage depth, solar panels, and the overall health of the home's systems. See buying a home remotely during a PCS.
3. House-hunting trip, or buying from a distance
If you can come out, you'll usually see around 10 homes and learn the areas at the same time. If you can't, some military buyers purchase without seeing the home in person, after a thorough video review and inspection. I help you get the information you need, connect you with the right people, and think it through, so you can choose what fits your timeline.
4. Under contract to closing, even before you arrive
I keep you on every Colorado contract deadline, and the title company coordinates your signing, including remote signing. Before you wire any money, confirm the wiring instructions by phone with the title company at a number you looked up yourself.
Leaving Colorado Springs on orders: sell, rent, or keep
When orders come, we run the numbers before you decide. If you might rent, we look at what the home could rent for and the full monthly cost, and I refer you to property management companies. If you might sell, I prepare a net sheet so you know what you'd walk away with. Then you choose.
If you sell after you've left
I sell empty homes all the time. I make sure the home is cleaned, staged, and ready to show as a home for sale, which is different from getting it ready for a renter. I arrange any repairs it needs: you hire and pay the contractors directly, and I make the connections, oversee the work, and let people in. Closing can be done remotely, and I arrange that too.
If you rent it out
Before you go, film the things a renter will need to know: changing the furnace filter, setting the thermostat, the sprinkler system, and where the water shutoff is. Those videos help your property manager and your renter, and they document the home's condition.
A real example: selling one home and buying the next on the same day
Moves rarely line up neatly, so planning matters. I've helped VA buyers close the sale of one home in the morning and buy their next home that afternoon, using the entitlement restored by the sale. In another move, a family was selling a home in Florida and buying in Colorado Springs the same day. Their loan officer advised signing the new loan outside Florida to avoid a Florida tax on the loan, so they drove to Alabama to sign and saved a couple thousand dollars. Every situation is different, but those are the details I watch for.
VA loans: what I watch for
I'm a Military Relocation Professional, not a loan officer, and the lenders I recommend all have VA experience.
I've helped clients close the sale of a home with a VA loan in the morning, have their VA entitlement restored, and use it to buy their next home that same afternoon.
That takes close coordination among the lenders and the title company, and it isn't possible in every situation.
I also work with the lender to compare costs before you decide how much to put down.
For a first-time VA purchase, for example, the VA funding fee is 2.15% of the loan amount with less than 5% down, 1.5% with 5% or more down, and 1.25% with 10% or more down.
Veterans who receive VA disability compensation are exempt from the fee. And I work with the lender to plan which seller concessions we can ask for to bring your costs down.
For the full picture, see buying a home with a VA loan in Colorado Springs.
The professionals I bring in
Part of my job is having the right people to call when something goes wrong, because in a move, something always does. I recommend values-aligned professionals, you choose, and I coordinate them around your orders.
Lenders: three VA-experienced options; you're free to choose anyone
Home inspector: one I recommend, whose work has served my clients well
Insurance: recommendations so you can compare coverage and deductibles
Property managers: referrals if you're keeping the home as a rental
Contractors, cleaners, and stagers: for getting a home ready to sell after you've left
Title and movers: coordinated to your report date
Team Hobbs Realty receives no referral fees from any of these professionals.
Why military families work with me
I've lived the moves. My family and I made more than 10 military moves, buying, selling, and keeping homes as rentals along the way.
Military Relocation Professional (MRP). I'm a U.S. Air Force Academy graduate and a retired Air Force veteran, and I work with every branch the same way.
I've used the VA loan myself. I know what to watch for on VA purchases, and I work alongside lenders who handle the loan.
I plan for the next move, not just this one. We decide up front whether this home should be one you could rent, sell, or come back to.
What clients say
From reviews clients posted on Google.
“When I worked with them, they provided guidance every step of the way, even when I couldn’t be present, to help make our PCS as smooth as possible.”
“Through our many moves with the Air Force, we have relied greatly on the knowledge and assistance of Weldon and Kristen. They really know what they’re doing because they too have experienced the highs and lows of moving during their time in uniform.”
“Weldon wasn't just helping us sell our house. He was a realtor turned friend giving us the honesty about all the options, which included possibly renting.”
Space Force: Peterson, Schriever, and Cheyenne Mountain
If you're a Guardian, or you're assigned to Peterson, Schriever, or Cheyenne Mountain, start with buying a home in Colorado Springs as a Guardian.
Fort Carson
If you're PCSing to Fort Carson, start with buying or renting when you're stationed at Fort Carson. It covers Fort Carson's own housing requirements, including checking in with the Housing Services Office before you commit to anything off post.
Air Force and the Air Force Academy
Air Force families here are assigned to the Academy, to Peterson (including joint commands such as NORAD and U.S. Northern Command), and to Cheyenne Mountain. I'm an Air Force Academy graduate and a retired Air Force veteran, and my family made more than 10 military moves.
Veterans and military retirees
Transitions are tough. If Colorado Springs was your last assignment, you probably know the area well. If you plan to buy here when you get out, it can help to buy while you're still on active duty.
Here's why. Lenders look at your work history to decide how much of your income they can count. Under Fannie Mae's guidelines for conventional loans, for example, lenders generally want a two-year history of self-employment income, and a two-year history is recommended for commission income, though as little as 12 months can sometimes be considered. For a regular W-2 job, lenders evaluate whether your work history over the most recent two years shows a reliable pattern. VA loans follow VA's own underwriting rules, so ask your lender how they would treat your situation.
There may be fewer hurdles if you buy while in uniform. That isn't guaranteed either way, so look into it with your lender before you separate or retire.
Military move questions: short answers
How early should I start buying before a PCS?
As soon as you have a realistic timeline, so financing, house-hunting leave, and closing line up with your report date. Read the full answer
Should I live on base or off base?
Start with your family's priorities and the base housing waitlist, then compare the full monthly cost of renting or buying off base. Read the full answer
Can I assume someone's VA loan?
Yes, VA loans are assumable, but it takes longer than a normal closing and you'll need to cover the gap between the price and the loan balance. Read the full answer
Is there a VA loan limit in El Paso County?
Not for borrowers with full entitlement; a limit applies only when part of your entitlement is still tied up. Read the full answer
How do I find an agent who understands military moves?
Ask how they handle remote buying, VA appraisals, and the decision to sell or rent when you leave. Read the full answer
All military questions
Search, or tap a topic to open it.
Every military move24 questions
- Is it better to rent or buy in Colorado Springs right now?
- Should I sell or rent my Colorado Springs home when I PCS?
- How early should I start buying a house before a PCS to Colorado Springs?
- Can I buy a Colorado Springs home remotely during a PCS?
- What is the difference between a VA appraisal and a home inspection in Colorado Springs?
- What happens if a VA appraisal comes in low in Colorado Springs?
- What are VA minimum property requirements when buying a home in Colorado Springs?
- How do VA seller concessions and closing costs work in Colorado Springs?
- Can I assume someone's VA loan in Colorado Springs?
- Should I look for a VA loan assumption in Colorado Springs when mortgage rates are higher?
- Is a Colorado Springs home a good long-term rental?
- What should I calculate before turning my Colorado Springs home into a rental?
- How should I compare FHA, conventional, and VA financing for a Colorado Springs home?
- Can I keep my Colorado Springs home as a rental and use my VA benefit again?
- How does BAH affect what a military family can realistically afford in Colorado Springs?
- What down payment assistance programs can first-time buyers use in Colorado Springs?
- How does mortgage pre-approval work, and how much does it matter when making an offer in Colorado Springs?
- How do I choose a lender for a VA loan in Colorado Springs?
- Is there a VA loan limit in El Paso County?
- How do I find a real estate agent who understands military moves and VA loans in Colorado Springs?
- Which Colorado Springs neighborhoods are in each school district?
- Should I live on base or off base when stationed in Colorado Springs?
- Should junior enlisted service members buy a home in Colorado Springs?
- What happens if my military orders change after I'm under contract on a Colorado Springs home?
Space Force: Peterson, Schriever, and Cheyenne Mountain1 question
Veterans and military retirees4 questions
Sources
- Peterson SFB Newcomers Information, Peterson and Schriever Space Force Bases
- Housing, U.S. Army Garrison Fort Carson
- VA funding fee and closing costs, U.S. Department of Veterans Affairs
- B3-3.2-01, Underwriting Factors and Documentation for a Self-Employed Borrower, Fannie Mae Selling Guide
- B3-3.2-02, Standards for Employment-Related Income, Fannie Mae Selling Guide
- Interest Rate Reduction Refinance Loan, U.S. Department of Veterans Affairs
Let's plan your move
Whether you're arriving, leaving, or deciding whether to keep your home, let's start with your orders, your timeline, and the numbers, so you can make the call with everything in front of you.